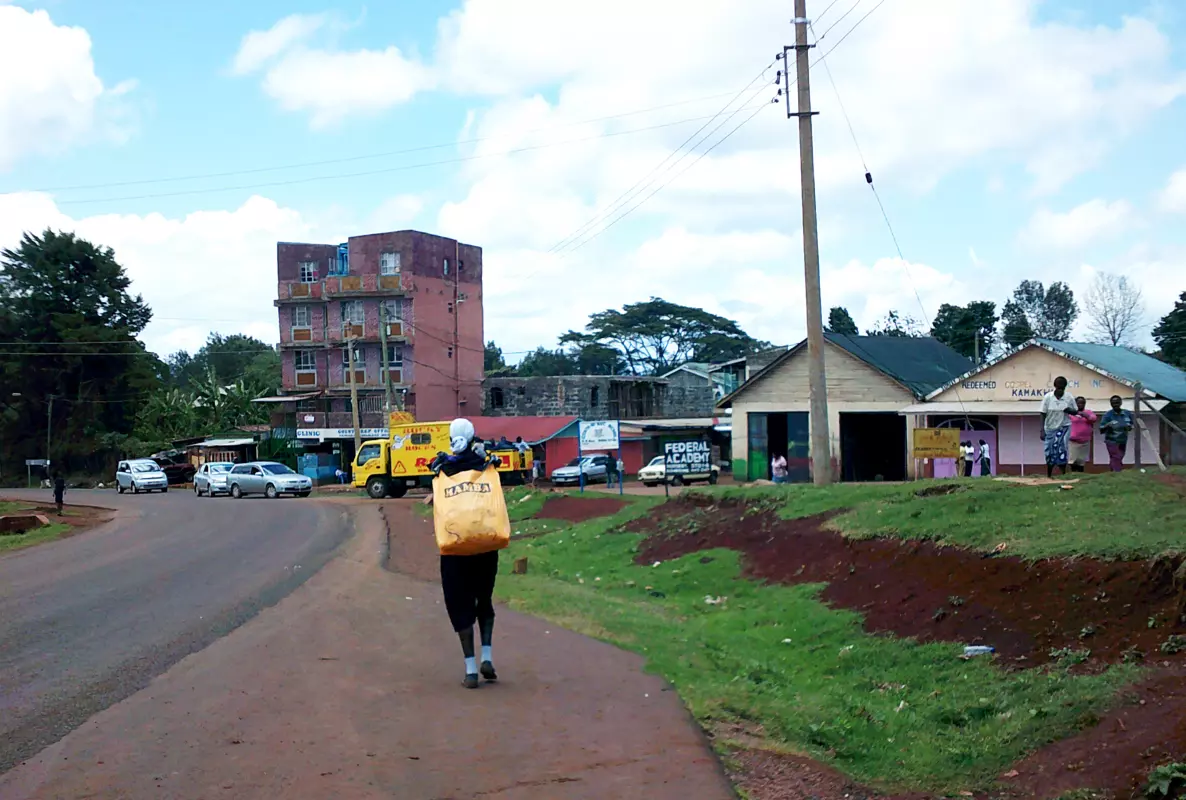
Early empirical work on microenterprises in developing countries suggested that small firms appeared to have extremely high returns to capital. For example, in their paper ‘Microenterprise growth and the flypaper effect: Evidence from a randomized experiment in Ghana’ (Journal of Development Economics, 2014) Marcel Fafchamps, David McKenzie, Simon Quinn, and Christopher Woodruff found that when small firms received capital grants, profits often rose sharply. If these firms were simply starved of capital, then expanding access to finance could unlock rapid growth.
In contrast, initial experimental research on microfinance painted a nuanced picture. For decades, the notion seemed simple: poor households and small entrepreneurs lacked access to capital, so providing small loans could enable investment, smooth consumption, and reduce poverty. Yet as microcredit expanded from a niche innovation into a global industry, a harder question emerged. If capital constraints were so severe, why did standard microcredit so often fail to generate transformative business growth? Over time, rigorous evaluations produced a more mixed and sometimes disappointing picture than early optimism had suggested.
In response, CSAE researchers have helped lead a shift in thinking – from asking whether finance matters to asking how financial products should be designed. Their work shows that the future of inclusive finance lies not simply in expanding access to credit, but in tailoring financial contracts to the scale, risks, and behavioural realities faced b
THE LIMITS OF THE CLASSIC LOAN
Traditional microcredit rests on a familiar structure: borrowers receive capital upfront and repay fixed instalments over time. This works well when returns are predictable. But for many small firms in low-income settings, returns are volatile, uncertain, and highly exposed to shocks.
This mismatch helps explain why simply expanding access to loans has not always delivered the hoped-for gains. Fixed repayment schedules can place substantial risk on entrepreneurs, discouraging them from undertaking risky but potentially high-return investments. Rather than unlocking growth, debt can sometimes constrain it.
Recognising these limitations, CSAE researchers have explored how financial products might be redesigned to better match the realities of smallscale enterprise.
WHEN MICROCREDIT IS TOO MICRO
One response has been to rethink not just the structure of loans, but their scale and purpose. In ‘Asset-Based Microfinance for Microenterprises: Evidence from Pakistan’ (Faisal Bari, Kashif Malik, Muhammad Meki, Simon Quinn, American Economic Review, 2024) CSAE researchers examine what happens when finance is explicitly linked to productive investment.
The project departs from traditional microcredit in two important ways. First, it substantially increases the amount of financing available, recognising that many meaningful business investments are “lumpy” and cannot be financed through very small loans. Second, it ties lending to the acquisition of specific productive assets, encouraging investment that directly supports business expansion.
The underlying insight is simple but important: for many firms, the problem is not just access to credit, but access to appropriately structured and sufficiently large capital. In this sense, microfinance may sometimes be “too micro” to support growth.
SAVING AND BORROWING: TWO SIDES OF THE SAME COIN
Another strand of CSAE research has focused on the relationship between borrowing and saving.
In ‘Two Sides of the Same Rupee? Comparing Demand for Microcredit and Microsaving in a Framed Field Experiment in Rural Pakistan’ (Uzma Afzal, Giovanna d’Adda, Marcel Fafchamps, Simon Quinn, and Farah Said, Economic Journal, 2018) CSAE researchers tested an idea that had been the subject of speculation in academic literature: that for many low-income households, both borrowing and saving can serve the same purpose, to accumulate lump sums.
This is especially true when households struggle to hold onto savings because of self-control problems or social pressure, while also needing large sums for investments or major purchases. Under these conditions, a loan and a commitment savings product may both function as mechanisms for disciplined accumulation.
This was a major conceptual breakthrough. It suggested that microcredit’s appeal may often reflect not demand for immediate consumption, but demand for commitment. Saving and borrowing were not opposites, instead they were alternative tools for solving the same behavioural problem.
COMMITMENT AS FINANCIAL INFRASTRUCTURE
This behavioural perspective deepened in ‘Demand for Commitment in Credit and Saving Contracts: A Field Experiment’ (Uzma Afzal, Giovanna d’Adda, Marcel Fafchamps, Simon Quinn, and Farah Said, Economic Journal, 2024).
Returning to Pakistan, the researchers tested how clients valued reminders, penalties, and flexibility in financial products. Their findings reinforced an important principle: many clients actively value discipline. Standard fixed repayment schedules, often criticised for rigidity, can themselves function as useful commitment devices, helping households manage temptation, inattention, or competing social demands. At the same time, different clients valued different combinations of flexibility and discipline depending on their financial habits. The lesson was clear: microfinance products should not simply be accessible; they should be behaviourally intelligent.
BEYOND DEBT: SHARING RISK
The most recent strand of CSAE research pushes beyond credit altogether. In ‘Microequity: Some Thoughts For An Emerging Research Agenda’ (Muhammad Meki and Simon Quinn, Oxford Review of Economic Policy, 2024), Meki and Quinn argue for the value of exploring an expanded suite of financing products, including performance-contingent contracts for some firms, what they term microequity.
Under these contracts, repayments vary with business performance, rising when profits are high and falling when they are low. Rather than placing all the risk on the entrepreneur, such arrangements allow risk to be shared between financier and firm.
This idea is explored empirically in ‘Small Firm Investment Under Uncertainty: The Role Of Equity Finance’ (Muhammad Meki, 2025). Drawing on experiments with growth-oriented small-firm owners in Kenya and Pakistan, the study shows that equity-like finance changes investment behaviour: entrepreneurs choose more profitable opportunities when contracts reduce downside risk. But the results also show that demand for equity-like finance depends on behavioural responses to risk, loss, and rare high-payoff states. This motivates hybrid contracts that preserve familiar debt-like features while adding capped performance-contingent repayment, reducing downside risk without requiring entrepreneurs to give up too much upside.
Complementary work in Finance and Mutuality: Experimental Evidence on Credit with Performance-Contingent Repayment (Francesco Cordaro, Marcel Fafchamps, Colin Mayer, Muhammad Meki, Simon Quinn, Kate Roll, 2025) tests such contractual innovations in practice, through a field experiment within a multinational supply chain in Kenya. By linking repayments to realised performance using administrative data, the study shows how risk-sharing finance can be made operational while generating gains for small distributors, local stockpoints, and the multinational firm. Together, this research positions as a plausible next step in the evolution of development finance.
LOOKING AHEAD: THE FUTURE OF INCLUSIVE FINANCE
As CSAE marks its 40th anniversary, this body of work illustrates a broader contribution combining rigorous field research with conceptual innovation to reshape how economists think about finance and development.
From early evidence on high returns to capital, to experiments with larger asset-based loans, to insights on savings, commitment, and risk-sharing, CSAE researchers have helped shift the conversation. Financial inclusion is no longer simply about expanding access to credit. It is about designing financial systems that match the scale of investment needs, the uncertainty of entrepreneurial environments, and the behavioural realities of households.
The future of development finance may lie not merely in more credit, but in better contracts: portfolios of savings tools, adaptive loans, and performance-contingent financing that together support growth and resilience. For millions of small entrepreneurs navigating uncertain environments, that shift could prove very valuable.
CSAE RESEARCHERS
Marcel Fafchamps
Muhammad Meki
Simon Quinn
Christopher Woodruff
PAPERS
Two Sides of the Same Rupee?
Comparing Demand for Microcredit and Microsaving in a Framed Field Experiment in Rural Pakistan
Authors: Uzma Afzal, Giovanna d’Adda, Marcel Fafchamps, Simon Quinn, Farah Said
The Economic Journal, Volume 128, Issue 614, September 2018
COVID-19 and the Future of Microfinance: Evidence and Insights from Pakistan
Authors: Kashif Malik, Muhammad Meki, Jonathan Morduch, Timothy Ogden, Simon Quinn, Farah Said
Oxford Review of Economic Policy, Volume 36, Issue Supplement_1, 2020
Microequity: Some Thoughts for an Emerging Research Agenda
Authors: Muhammad Meki, Simon Quinn
Oxford Review of Economic Policy, Volume 40, Issue 1, Spring 2024
Asset-Based Microfinance for Microenterprises: Evidence from Pakistan
Authors: Faisal Bari, Kashif Malik, Muhammad Meki, Simon Quinn
American Economic Review vol. 114, no. 2, February 2024
Small Firm Investment Under Uncertainty: The Role of Equity Finance
Author: Muhammad Meki
Oxford Department of International Development Working Paper, No.213, August 2024
Demand for Commitment in Credit and Saving Contracts
A Field Experiment
Authors: Uzma Afzal, Giovanna d’Adda, Marcel Fafchamps, Simon Quinn, Farah Said
The Economic Journal, Volume 134, Issue 664, November 2024
Finance and Mutuality
Experimental Evidence on Credit with Performance-Contingent Repayment
Authors: Francesco Cordaro, Marcel Fafchamps, Colin Mayer, Muhammad Meki, Simon Quinn, Kate Roll
May 2025